Nick Francia
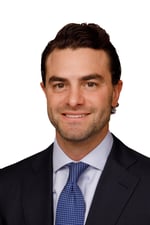
Nick joined UBS in 2011. As a member of The Capital ESOP Group, Nick focuses on educating business owners on different tax-efficient monetization strategies, empowering them to make informed decisions. Nick also creates tailored cash flow models comparing the taxable sale of privately held businesses and a Section 1042 tax-deferred sale to an ESOP. In 2018 Nick was recognized by Forbes as one of America's Top Next-Generation Wealth Advisors. Nick graduated from the University of Mary Washington, where he earned a bachelor's degree in economics.